informação
Informação
Conhecimento especializado em residência, imobiliário, património e estilo de vida, tudo num só lugar
Notícias e Artigos

Notícias e Artigos
Mantenha-se a par das últimas novidades sobre residência, imobiliário e fiscalidade em Portugal
Vídeos de Análise

Vídeos de Análise
Veja vídeos sobre o estilo de vida e localizações, registos de eventos passados, opiniões de especialistas e histórias de clientes
Explorar Localizações
Explorar Localizações
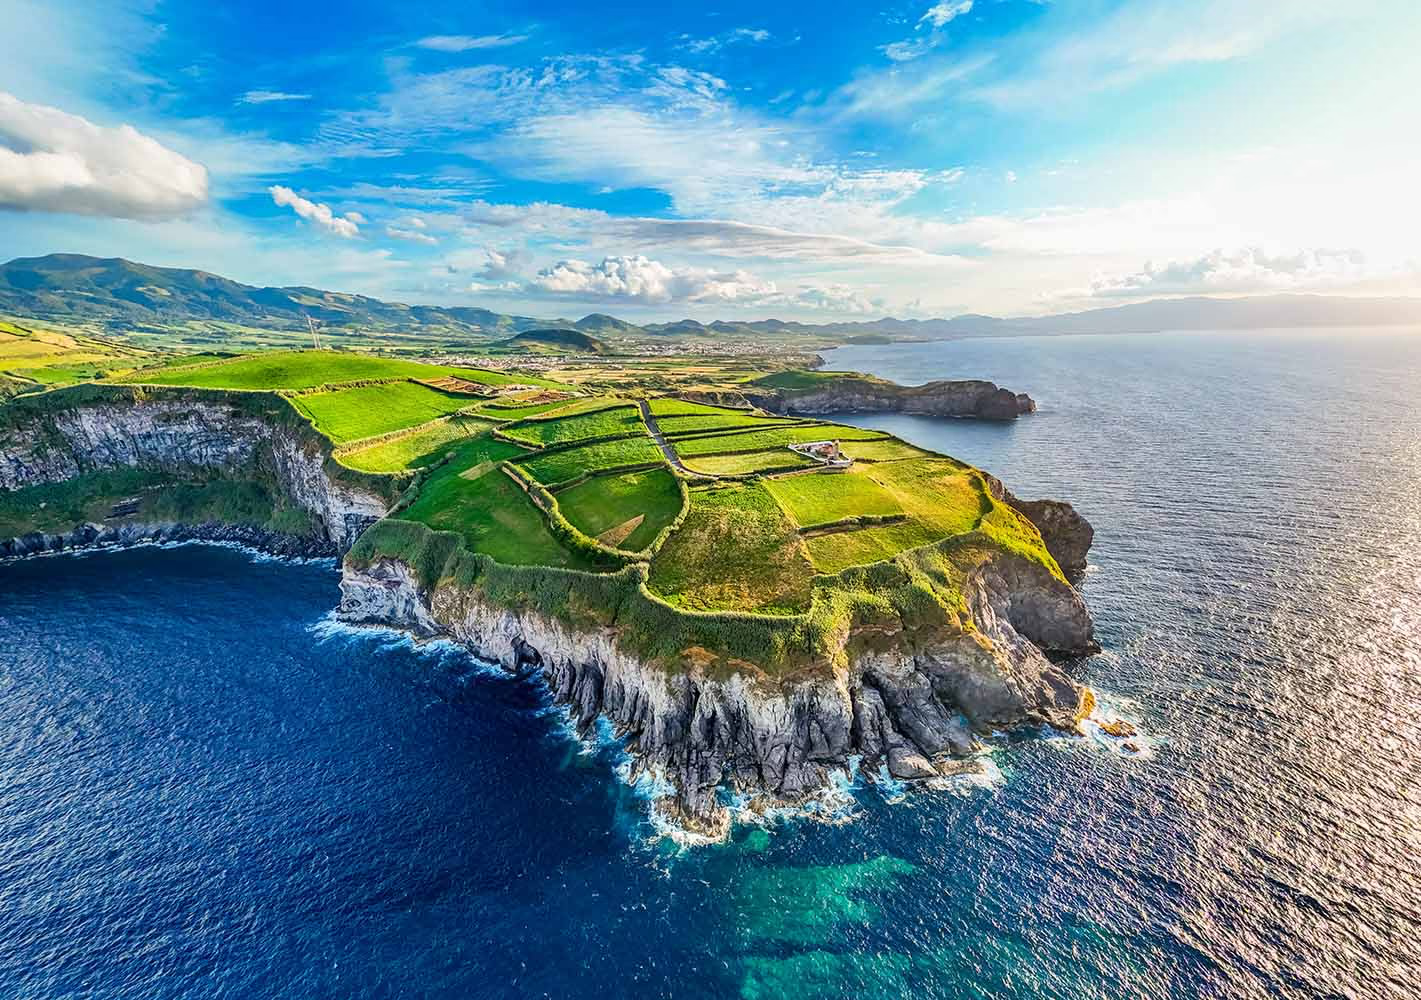
Encontre o local que se adapta ao seu estilo de vida, da tranquilidade da costa à energia da cidade
Guias e Whitepapers
Guias e Whitepapers
Aprofunde os seus conhecimentos com guias completos e whitepapers sobre residência, planeamento fiscal e de património, e imobiliário
Eventos e Webinars

Eventos e Webinars
Participe em sessões em direto com os nossos consultores e especialistas para ouvir as orientações mais recentes
FAQ / Fale com um Especialista
FAQ / Fale com um Especialista
Obtenha respostas claras às suas perguntas, diretamente da nossa equipa de especialistas
Casos de Estudo
Casos de Estudo
Veja como ajudámos clientes a mudar-se, investir e proteger o seu património
soluções

Soluções
Apoio integral em vistos, imobiliário, gestão de património, fiscalidade e concierge
Visto Gold

1134602318
Visto Gold
O principal programa de residência por investimento da Europa
Visto D7

Visto D7
Garanta a sua residência em Portugal
Visto de Nómada Digital D8

1135818928
Visto de Nómada Digital D8
Desfrute da liberdade do estilo de vida de nómada digital
Visto de Empreendedor D2
1132569453
Visto de Empreendedor D2
Visto D2 em Portugal – Como se qualificar para um Visto de Empreendedor
Ver tudo

Ver tudo
Opções de residência alinhadas com os seus objetivos e metas
Casas de Luxo Novas

1170759853
Casas de Luxo Novas
As casas de luxo novas mais exclusivas de Portugal, em planta e fora do mercado
Soluções de crédito habitação

1135492330
Soluções de crédito habitação
Compare todo o mercado e encontre a melhor oferta de crédito habitação
Soluções de compra

1135829726
Soluções de compra
Aceda a casas de luxo novas em Portugal
Ver tudo

1203745208
Ver tudo
Aceda a casas de luxo novas, em planta ou fora do mercado, em Portugal, com apoio total na compra
Planeamento fiscal e sucessório

1135810494
Planeamento fiscal e sucessório
Planeamento fiscal transfronteiriço para Portugal
Estratégias de investimento

1135805765
Estratégias de investimento
Invista em Portugal com confiança
Planear o fim do RNH

1134629238
Planear o fim do RNH
Planeie com antecedência antes do fim do seu estatuto fiscal de RNH
Regime Fiscal IFICI (RNH 2.0)

1134645426
Regime Fiscal IFICI (RNH 2.0)
Explore o Regime Fiscal IFICI de Portugal
Ver tudo

Ver tudo
Gestão de património e fiscalidade transfronteiriça, alinhada com a vida e o investimento em Portugal
Seguro de Saúde Privado

1134688776
Seguro de Saúde Privado
Proteja a sua saúde em Portugal e no estrangeiro
Câmbio de Moeda Estrangeira

1135482679
Câmbio de Moeda Estrangeira
Faça pagamentos internacionais transparentes e mais económicos
Constituição de Empresas

1134683456
Constituição de Empresas
Simplificar a Gestão e a Constituição de Empresas em Portugal
Ver tudo

1202736580
Ver tudo
Desde seguros de saúde, educação e constituição de empresas até à prospeção de locais e retiros de bem-estar exclusivos
Sobre nós